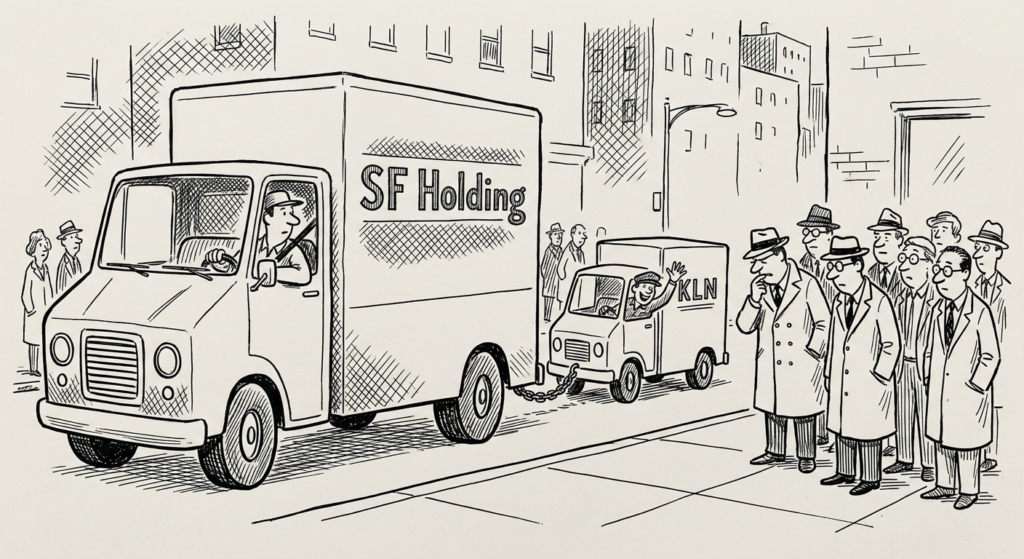
The former Kerry Logistics Network delivered a solid-looking first half, until you compare revenue growth with profit growth and start asking where the margin went.
KLN Logistics Group, the Hong Kong-listed forwarder that rebranded from Kerry Logistics Network in March 2025, reported first-half 2026 revenue of HK$29.85 billion, up 10% year on year. In a market where Hong Kong logistics operators have spent the past 18 months dodging tariff escalations, softening China-Europe volumes and the steady gravitational pull of Shenzhen absorbing traffic that once transited through the city, double-digit top-line growth is the kind of number that gets circled on a results screen.
Then you look at the rest of the page. Core operating profit fell 8%, to HK$1.24 billion. Profit attributable to shareholders rose just 4%, to HK$674 million. And both of KLN’s core divisions, integrated logistics and international freight forwarding, posted segment profit declines of 7% each, even as both divisions grew revenue by 19% and 12% respectively.
Revenue up. Costs up faster. Margins squeezed. The company says this was driven by customer-led rate reductions, inventory destocking, higher fuel costs that could not be fully passed through, and competitive pressure across forwarding lanes. In other words, KLN chose to protect volume and customer relationships over short-term margin. That is a defensible strategy in a soft market, but it is not a comfortable one.
The SF Holding question
No assessment of KLN’s results makes sense without addressing who owns it. SF Holding, the Shenzhen-based express and logistics giant, acquired a 51.8% controlling stake in the then-Kerry Logistics Network for HK$17.55 billion in 2021, in a single transaction that reduced the Kuok family’s Kerry Holdings from majority owner to minority shareholder. KLN is now, functionally, SF’s international arm: its bridge into Southeast Asia, the Middle East, Europe and the Americas.
SF Holding’s own first-half results, published the same day, make the dynamic plain. The parent’s supply chain and international revenue rose 15.6% year on year. Strip out KLN, and SF’s own international revenue surged 46.6%, with its international supply chain business (again, excluding KLN) up 155%. SF is not waiting for KLN to be its sole international growth vehicle. It is building parallel capacity at speed.
That raises an uncomfortable question for anyone analyzing KLN as a standalone entity. How much of KLN’s 10% revenue growth is organic, won in competitive tenders against the likes of Kuehne+Nagel and DHL, and how much reflects SF routing international volumes through a subsidiary it controls? KLN’s results announcement did not break out internal versus external revenue. Until it does, that question will sit unanswered at the center of every earnings analysis.
Where the margin went
The segment-level detail is where the real story sits. KLN’s integrated logistics arm grew revenue 19%, driven by roughly 60 new customer wins in Hong Kong and expansion in mainland Chinese cold chain and commodity transport. Hong Kong revenue alone jumped 26%. But segment profit fell 7% to HK$665 million. The company attributed the decline to customers pushing rates down, inventory destocking and fuel costs it could not recover.
International freight forwarding told the same story from a different angle. Revenue grew 12%, with what KLN described as strong volume growth across both air and ocean freight. Segment profit still fell 7%, to HK$855 million. The company said competitive market pressure and higher fuel costs that it chose not to pass through were the main culprits, noting that it prioritized maintaining customer relationships.
Read those two segments together and a pattern emerges: KLN is buying market share at the expense of profitability. The project logistics division was the only segment where both revenue and profit moved in the right direction, with revenue rising to approximately HK$1.9 billion from HK$1.7 billion a year earlier, supported by ongoing EPC contract execution.
CEO Vic Cheung framed the results around resilience, noting that “geopolitical tensions, tariff uncertainty and uneven economic conditions in major markets continued to shape global trade and supply chains in the first half of 2026.” He pointed to the China Plus One sourcing trend and continued investment in AI infrastructure as supporting volume, particularly on Asia-to-US lanes.
A net margin of 2.3% on nearly HK$30 billion of revenue
The company did increase its interim dividend to 12 HK cents per share, up 9% year on year. That signals confidence in cash generation. But a net margin of roughly 2.3% on HK$29.85 billion of revenue is not a business swimming in pricing power. It is a business running hard to stay in place, hoping that scale eventually converts into earnings leverage.
KLN’s management has flagged a “KLN 2.0” strategy, described as a new phase of capability-building set to follow the post-acquisition integration period. The details remain thin, but the branding tells you something: SF Holding sees KLN’s network, license portfolio and customer relationships as the scaffolding for its next international push, particularly in markets where a mainland Chinese parent company might face political friction operating directly under its own name.
For competitors and investors, the questions that matter are straightforward. Can KLN defend margins while SF uses it as a volume conduit? Will KLN 2.0 deliver genuine operational improvement, or is it a rebadging exercise for SF’s international ambitions? And as SF builds its own parallel international capacity at a pace that dwarfs KLN’s organic growth, how long does the Hong Kong-listed subsidiary retain strategic relevance?
The 10% headline is real. Whether it reflects competitive strength or structural dependence is the question these results cannot quite answer.