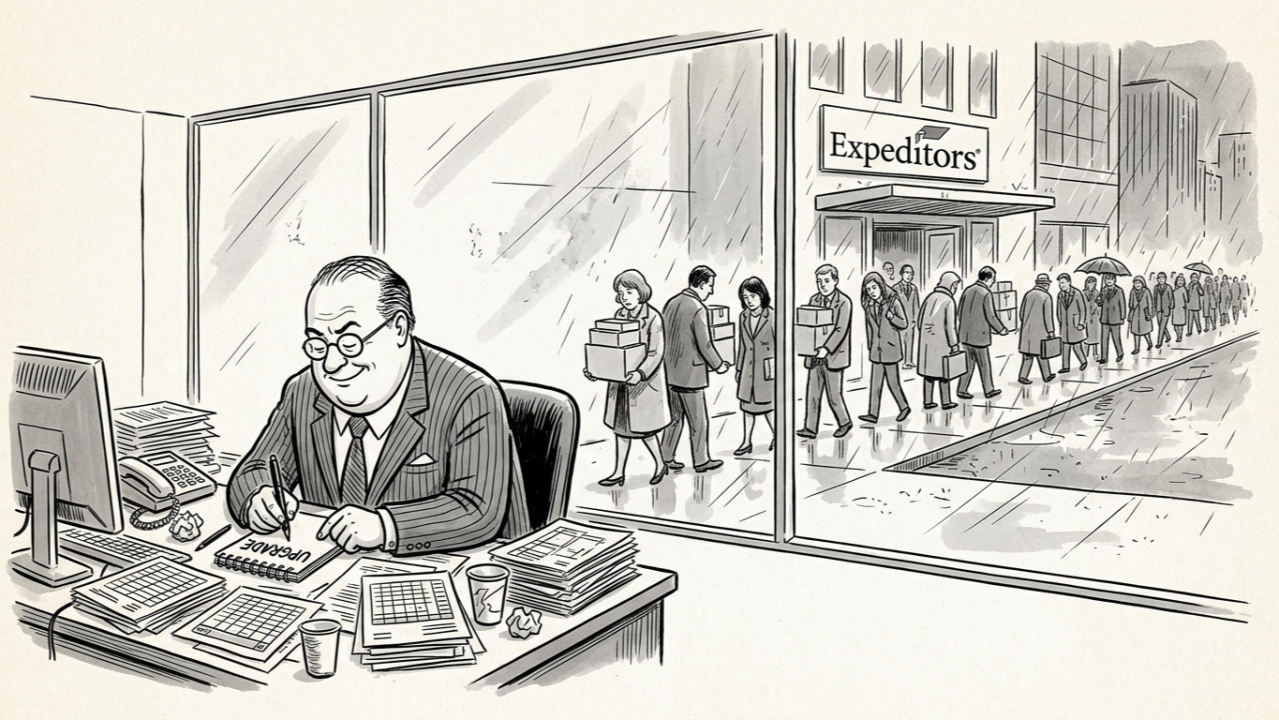
On August 5, 2026, J.P. Morgan analyst Brian Ossenbeck upgraded Expeditors International from Underweight to Neutral and raised his price target from $144 to $200. He had rated the stock Underweight for nearly three years. Through nine consecutive quarters, he watched the company beat earnings eight times, and still he would not budge. Something finally changed his mind.
It was not a new product. It was not a new market. It was not a technological breakthrough that made the company more competitive or a strategic acquisition that expanded its reach. What changed his mind was what he called an “unprecedented restructuring effort” by the company’s relatively new senior management team, one that had “quietly reshaped the company’s structure and cost profile.”
Quietly reshaped. That is a beautiful phrase. It is the kind of phrase that sounds like praise on an earnings call and sounds like something else entirely when you are the structure being reshaped, when quietly means no one told you until a stranger read you a paragraph, and reshaped means your desk was cleared by lunch.
I have spent months documenting what that quiet reshaping looked like from the inside. The locked email. The Monday. The scripts read by strangers who could not answer a single question. The bootcamp that made employees audition for jobs they already had. The CIO who told twenty-year veterans the promise never existed. The federal docket where the company’s lawyers called forty years of trust “precisely the type of vague assurance that courts have rejected.”
I wrote about the Desecrator who swung the axe and invoked Peter Rose’s name while doing it. I wrote about the Machinist who built the legal architecture that made the destruction look like paperwork. I wrote about Kevin the Mute, the ethics officer who promised day or night and delivered silence. I wrote about the Bouncer, the paid vendor who told the people inside a building he has never worked in to leave if they don’t like it. I wrote about the arithmetic of extraction, the twelve billion returned to shareholders while two hundred and thirty people were converted into EPS. I wrote about Glenn Alger, the last founder in the room, sitting on sixty million dollars in stock and saying nothing while the lawyers called his life’s work a fiction. I wrote the closing argument. I wrote the epilogue.
AND NOW J.P. MORGAN HAS WRITTEN THE REVIEW.
THEY LOVED IT.
Ossenbeck’s note does not use the word “layoffs.” It uses the word “restructuring.” It does not mention the people who lost their jobs. It mentions a $25 million pretax restructuring charge, which it describes as having been “partially offset” by a $16 million property sale gain. The humans are a line item. The building is the offset. The net cost of reshaping the lives of more than two hundred and thirty people and their families is, in the analyst’s model, nine million dollars. That is less than Dan Wall made in his first year as CEO.
The note frames the restructuring not as a cost but as a catalyst. Ossenbeck draws a direct comparison to C.H. Robinson, the company I profiled in an earlier essay, the one that has shed 5,500 jobs in three years while its CEO tells Fortune it is not about mass layoffs. The comparison is not cautionary. It is aspirational. The note includes a chart, headcount at both companies plotted side by side, with a notation that the “effect of layoffs will begin in 3Q26.” The implication is unmistakable. Robinson cut heads. Robinson’s stock doubled. Expeditors is doing the same thing. The stock should follow.
FEWER PEOPLE. SAME OUTPUT. BETTER MARGINS. HIGHER MULTIPLE.
The analyst is not describing a company that made a painful decision. He is describing a company that found a lever and is being rewarded for pulling it.
To his credit, Ossenbeck asks the right question. Buried on page three, in a list of ten “key questions for consideration,” is this: “Expeditors has long been known for having a no-layoff culture, how has a restructuring of this size affected morale, retention, and the broader culture within the firm?” He asks it. He does not answer it. He does not need to answer it, because the answer is not in his model. His model has a line for operating expenses and a line for EPS and a line for the price-to-earnings multiple, and none of those lines captures what happens when a twenty-year veteran posts online that she still does not know how to process the news, or when a daughter writes that her mother was laid off and the family depended on her for health insurance, or when a surviving employee describes the bootcamp as a predator playing with its food.
THE MODEL DOES NOT CAPTURE THE DRIVE HOME. The model does not capture the engine idling in the driveway while someone rehearses the words. The model does not capture the kitchen table.
But the model does capture this: Ossenbeck raised his EPS estimate for 2026 from $6.98 to $7.60, an 8.8 percent increase. For 2027, from $7.38 to $8.30, a 12.4 percent increase. The price target went from $144 to $200 based on a 22x multiple applied to 2028 estimated earnings of $9.10. He removed the 2.5x discount he had previously applied to the stock’s long-term average multiple. The discount had been there for years. What removed it was the restructuring. The company earned its way back to the average multiple not by growing faster or innovating more or serving customers better. It earned it by cutting people. The multiple expanded because the heads contracted. That is the arithmetic I described in the extraction essay, rendered in the language of a sell-side research note and distributed to every institutional investor on J.P. Morgan’s platform.
And notice the valuation framework. The price target is built on 2028 estimated earnings. The layoffs happened in June 2026. The savings flow into operating income starting in the third quarter of 2026. By 2028, the full annualized benefit, thirty-five to forty-six million dollars in eliminated salaries, is baked into the earnings the analyst is capitalizing at 22x. That means every dollar of salary that disappeared when a stranger read a paragraph and pointed at a door is being multiplied twenty-two times in the analyst’s model and added to the price target that tells institutional investors what the stock is worth. The terminated employee’s annual compensation is not just saved. It is capitalized. It is multiplied. It is converted into market value at a ratio that makes the extraction I described not merely visible but mathematically precise. A person who earned $150,000 a year is not worth $150,000 to the stock price. That person’s absence is worth $3.3 million. Their removal is more valuable than their career.
MORE CUTS. MORE SAVINGS. MORE EPS. MORE MULTIPLE EXPANSION.
Ossenbeck also notes something that should concern every employee still inside the building. He asks whether the restructuring is complete, or whether further headcount reductions should be expected, and whether those will be concentrated in Global Technology or extend to other functions. He is not asking because he is worried. He is asking because he wants to know if there is more upside. The analyst is not hoping the restructuring is finished. He is hoping it is just starting.
And he sees the November 2026 investor day in New York as “the next logical catalyst.” A catalyst. That is the word. The day the company stands in front of Wall Street and explains what it plans to do next with its cost structure, its headcount, its “productivity story,” is not a moment of reckoning. It is a catalyst. A thing that makes the stock go up. The employees who are still updating their resumes and wondering if the bootcamp was a filter and watching for the same preparatory signals they failed to recognize before the Monday, those employees are living inside a catalyst. They just did not know that catalyst was the word for it.
I wrote in the extraction essay that the layoff is not a separate decision from the buyback. The layoff is the buyback. The people are being converted into shares, their salaries alchemized into EPS, their careers burned as fuel to power the engine that makes executives rich. J.P. Morgan’s upgrade note is the receipt. It is the institutional confirmation, printed on letterhead, distributed to every fund manager on the platform, that the conversion worked. The fuel burned cleanly. The engine produced the expected output. And the analyst, who watched from the outside for three years and would not upgrade the stock through eight out of nine earnings beats, finally saw what he needed to see. Not better freight rates. Not stronger customer relationships. Not a more durable competitive position. He saw the cuts. And he upgraded.
The note also raises a question that deserves to sit in every employee’s chest for a while. He asks whether Expeditors can still meet its AI and technology objectives after cutting the team responsible for building them, and whether it will lean on third-party contractors to fill the gaps. That is a polite way of saying the company may have just fired the people it needs most and will end up paying more to replace them with outside vendors who have no institutional knowledge, no cultural memory, and no reason to stay past the end of the contract. The people who built the systems the company still runs on are on LinkedIn right now, composing careful sentences about new chapters. The company that trained them, specialized them, made their skills untranslatable to any other employer’s tech stack, and then eliminated them, will now pay a consulting firm three times the hourly rate to do what those people did for a salary and a promise. The promise is gone. The salary is gone. The consulting invoice is coming. And the analyst calls it a productivity story.
NOT BECAUSE THE COMPANY GOT BETTER. BECAUSE THE COMPANY GOT SMALLER.
I want to be precise about what is happening, because the language matters. An analyst who had the stock rated Underweight for three years, who watched Expeditors beat earnings eight out of nine quarters and still would not upgrade, who maintained a below-consensus price target through a 55 percent rally, changed his mind because the company started firing people. The upgrade is not a vote of confidence in what Expeditors is building. It is a vote of confidence in what Expeditors is dismantling. The analyst is not saying the company is worth more because it is stronger. He is saying the company is worth more because it is lighter. And lighter, in this context, means two hundred and thirty fewer families with health insurance.
That is what the stock market sounds like when it is working as designed. It is not broken. It is not corrupt. It is doing exactly what it was built to do, which is to assign a number to the future cash flows of an enterprise and update that number when the inputs change. The inputs changed. Two hundred and thirty salaries exited the model. The number went up. The system does not have a field for the parking lot where someone sat with the engine running. The system does not have a field for the daughter doing math that does not work. The system has a field for operating expenses, and operating expenses went down, and the number went up.
In Adams, Massachusetts, when the mills closed, nobody upgraded the stock. There was no stock. There was just a building and a silence and a town that got quieter and never got loud again. But the arithmetic was the same. Fewer people. Lower costs. The margin preserved for the people who owned the capital. The difference is that in Adams, at least nobody pretended it was good news. Nobody published a note with a price target and a buy rating and a chart showing how many more people could be cut before the productivity story was fully priced in. Nobody called the closing of the Waverly mill a catalyst.
Dan the Desecrator swung the axe. The Machinist built the architecture. Kevin the Mute watched from the tower. The Bouncer sold the breach. And now J.P. Morgan has put a price on it.
$200.
That is what your career was worth. Not to you. To the model. Your absence, capitalized at 22x, contributed to a price target that will be used by every fund manager on the platform to decide whether to buy more of the company that walked you out of the building. Your termination is not a loss in their framework. It is an input. A positive one. The kind that moves a stock from Underweight to Neutral and a target from $144 to $200.
WALL STREET HAS SPOKEN. IT LOOKED AT WHAT EXPEDITORS DID TO ITS PEOPLE AND IT SAID: DO MORE.
The other people in the room had better ideas. The analyst’s model just didn’t have a field for them.